What Happens if the Buyer’s Financing Falls Through at the Last Minute?
Getting a clear to close from a mortgage lender is usually a cause for celebration in a real estate transaction. However, loans are sometimes unexpectedly denied days before the final signing appointment. This sudden reversal leaves both buyers and sellers scrambling to figure out their legal and financial next steps.
A last-minute funding failure shatters carefully planned moves and can trigger complex legal disputes. Understanding why this happens and how to react can help you salvage your finances and protect your sanity.
The Impact of a Financing Failure
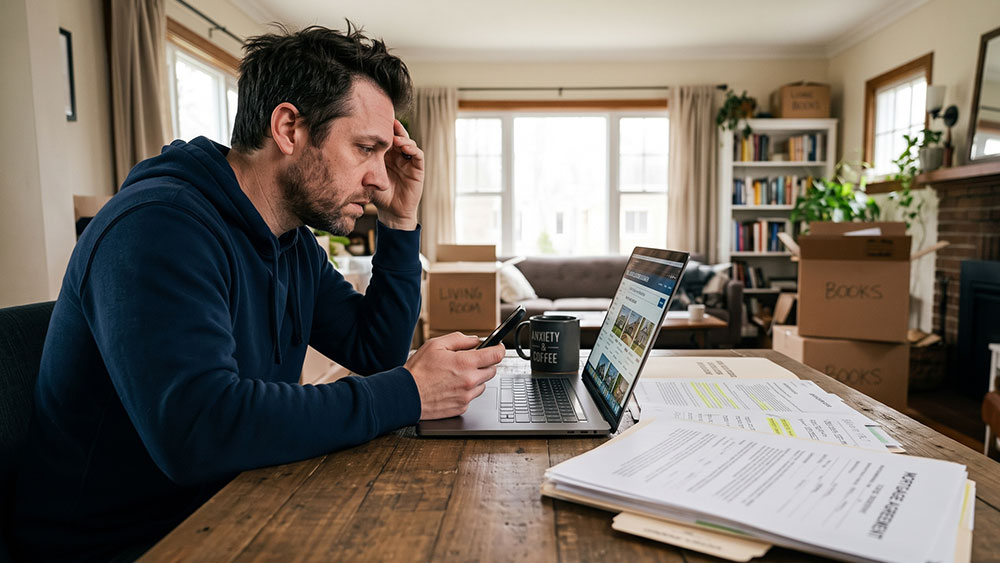
A last-minute mortgage denial creates a massive logistical nightmare for everyone involved in the property transfer. Sellers are often completely packed and ready to move, assuming the funds will arrive flawlessly on closing day. Buyers face the devastating reality of losing their dream home alongside the money they already spent on inspections.
The Seller’s Frustration and Costs
Sellers suddenly find themselves stuck with a vacant home and a renewed mortgage payment they planned to eliminate. They must relist the property immediately, extending their timeline and adding carrying costs. This delay is especially agonizing if the seller is trying to buy another home at the same time.
The longer the property sits back on the market, the more a seller’s negotiating power completely evaporates. Buyers often view relisted homes with deep suspicion, assuming a massive inspection issue caused the previous cancellation.
The Buyer’s Lost Investment
Buyers lose more than the chance to buy the specific house they fell in love with. They forfeit non-refundable fees paid for home inspections, pest assessments, and the official bank appraisal. They also face intense emotional distress and the daunting task of finding alternative housing on a condensed timeline.
Buyers must abruptly cancel moving trucks and frantically negotiate apartment lease extensions. The financial and emotional toll of a failed transaction can set a buyer’s goals back for months.
Understanding the Financing Contingency
The financial fallout of a canceled deal depends entirely on the language in the purchase agreement. Real estate contracts heavily rely on protective clauses called contingencies to shield both parties from unexpected disasters. The financing contingency is the most critical safeguard for buyers who need a mortgage loan.
How the Contingency Protects the Buyer
This clause states that the entire transaction depends on the buyer securing formal loan approval. If the lender ultimately denies the mortgage application, this contingency allows the buyer to legally cancel the deal. The buyer can walk away cleanly without facing lawsuits for a sudden breach of contract.
This protection relies entirely on the buyer acting in good faith throughout the entire underwriting process. Lenders will issue formal denial letters explaining the exact financial reason the mortgage could not be funded.
Expiration Dates and Waivers
Financing contingencies do not remain active indefinitely throughout the entire escrow process. They typically expire after three or four weeks, requiring the buyer to secure full approval within that window. If the buyer waives this protection early to strengthen their offer, they assume significant financial risk.
In highly competitive markets, buyers sometimes waive this contingency entirely to beat out multiple competing cash offers. If their loan subsequently fails without this protection, the financial consequences are incredibly severe.
Reasons Loans Get Denied Late
Underwriting is a rigorous and highly detailed process that continues right up until the official day of closing. Lenders pull a final credit report just hours before funding to ensure the borrower’s financial profile remains stable. Even a slight change in income or debt can trigger an automatic rejection by the underwriting software.
Sudden Job Loss or Income Changes
Lenders base large loan approvals on the borrower’s steady, predictable income stream. If a buyer suddenly loses their job right before closing, the bank immediately revokes the mortgage offer. Even a voluntary career change or a shift from salary to commission can sabotage the final approval.
Mortgage companies must verbally verify employment on the day the loan is scheduled to fund. Any hint of employment instability will bring the entire closing process to a screeching halt.
Taking on New Debt
Buyers frequently make the disastrous mistake of financing new furniture or a car before closing on their house. Opening new credit lines alters the buyer’s strict debt-to-income ratio, making them ineligible for the original loan amount. Lenders strictly forbid large credit purchases during the delicate escrow period for this exact reason.
Even cosigning a student loan for a family member can completely derail a massive real estate transaction. Buyers must freeze spending and avoid new credit inquiries until they have the house keys in hand.
The Role of the Real Estate Appraisal
The formal property appraisal is closely tied to the buyer’s ability to secure final mortgage financing. Lenders will absolutely refuse to fund a loan if the home appraises for significantly less than the purchase price. This valuation gap can become a sudden roadblock that derails a deal right before closing.
Navigating a Low Appraisal
If the appraisal comes in low, the lender drastically reduces the maximum loan amount they are willing to offer. The buyer must either bring additional cash to the closing table or successfully negotiate a lower purchase price. If neither party yields, the lender officially denies the financing, and the transaction is immediately canceled.
Challenging the Appraiser’s Value
Buyers and sellers can occasionally collaborate to challenge a flawed appraisal report by submitting a formal reconsideration of value. This process requires the real estate agents to provide better comparable sales data to the original appraiser. If the appraiser refuses to adjust their final number, the buyer’s financing remains permanently stalled.
What Happens to the Earnest Money?
The earnest money deposit becomes the primary battleground when a property transaction collapses unexpectedly. This upfront cash deposit sits in a neutral escrow account while the parties negotiate the cancellation terms. Determining who legally keeps these funds requires a careful examination of the contract’s specific expiration dates.
Scenarios Where the Buyer Gets a Refund
Buyers usually recover their entire earnest money deposit if their financing contingency remains fully active. They provide the seller with the official loan denial letter from their mortgage bank. The title company will require both parties to sign a release form before sending the funds back to the buyer.
Scenarios Where the Seller Keeps the Cash
Sellers are entitled to the deposit if the buyer’s financing fails after the specific contingency deadline has passed. The seller keeps this money as compensation for taking their property off the active market for several weeks.
- Sellers also retain the deposit if the buyer deliberately sabotaged their own loan approval.
- Waiving the financing contingency upfront guarantees the seller keeps the earnest money if the loan fails.
Strategies to Save the Transaction
A loan denial does not always guarantee the immediate death of a real estate transaction. Sellers who desperately want to avoid relisting the property might agree to exercise incredible patience. Buyers and their agents can sometimes salvage the deal by using fast alternative funding solutions.
Extending the Closing Date
If a simple administrative error caused the loan denial, the bank might need more time. The buyer’s agent can draft an official contract addendum pushing the closing date back by a few weeks. The seller must voluntarily sign this extension, giving the buyer’s lender adequate time to correct the paperwork issue.
Finding Alternative Lenders
A denial from a strict traditional bank does not preclude the buyer from qualifying with a different institution. Mortgage brokers have access to specialized lenders with much looser underwriting guidelines for borderline borrowers. This rapid transition requires the seller to grant a massive extension while the new lender completely restarts the loan process.
These alternative loans often come with much higher interest rates and drastically increased closing costs. The buyer must quickly decide if acquiring the property is worth the sudden financial penalty of a subprime mortgage.
Moving Forward After a Canceled Sale
Sometimes a transaction is too broken to save, forcing both parties to accept the harsh reality. Sellers must pivot their strategy immediately to minimize their total days on the market. Buyers must pause their property search and aggressively repair whatever financial damage caused their sudden loan denial.
Relisting the Property Quickly
Sellers need their listing agent to update the property’s online status from pending to active immediately. A skilled agent will contact every buyer who previously showed interest in the home to announce its sudden availability. Transparent communication about why the deal failed prevents new buyers from assuming the house has hidden physical defects.
Reassessing Buyer Qualifications
Before accepting a new offer, sellers should demand a highly rigorous pre-approval letter from a reputable local lender. The listing agent should personally call the buyer’s loan officer to verify that their income and assets were fully vetted.
- Asking for a larger earnest money deposit helps filter out buyers with fragile financial profiles.
- Sellers can prioritize buyers using conventional loans over strict government-backed financing to reduce future underwriting risks.
Closing Points
A last-minute financing failure is one of the most stressful experiences a homebuyer or seller can face. The collapse of the transaction triggers immediate logistical chaos and initiates intense legal debates over the earnest money deposit. Understanding how contingencies work and why loans suddenly fall apart helps both parties navigate the fallout.
By staying calm and evaluating alternative funding options, you can sometimes rescue a failing deal from total collapse. If the transaction is truly unsalvageable, swift and decisive action is required to minimize financial losses. Sellers must relist aggressively, while buyers must take time to fortify their financial profiles before attempting to purchase real estate again.