What is Earnest Money and How Much Should You Offer?
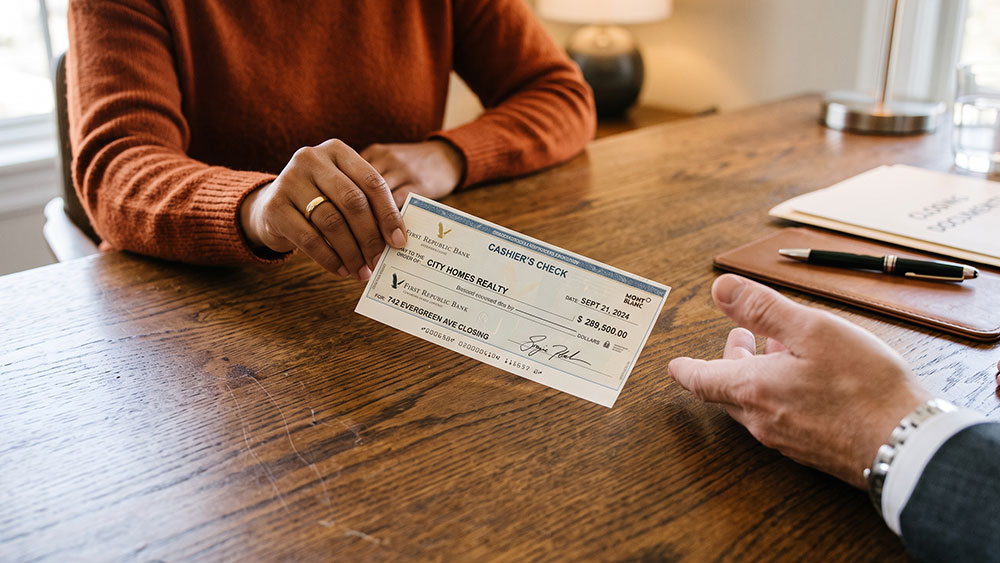
Buying a home involves several financial milestones long before you sign the final mortgage documents. One of the earliest and most critical financial commitments is the earnest money deposit. This upfront payment serves as tangible proof that a buyer is serious about purchasing the property.
Without it, sellers would have no security when taking their home off the active market. Understanding how this deposit functions can make or break your real estate transaction.
The True Purpose of Earnest Money
When a seller accepts an offer, they immediately stop marketing the property to other prospective buyers. The earnest money deposit acts as a financial security blanket for the seller during the lengthy escrow process. If the buyer walks away for an unapproved reason, the seller keeps the money as compensation.
Protecting the Seller’s Time
A standard real estate transaction takes several weeks to close fully. During this period, the seller completely removes their property from the active housing market. If the deal falls through maliciously, the seller loses valuable marketing time and potential competing offers.
Proving Buyer Intent
Talk is incredibly cheap in the highly competitive world of real estate. Anyone can submit a written offer, but writing a check requires genuine financial commitment. Earnest money separates casual window shoppers from highly motivated, qualified buyers ready to close.
How Much Earnest Money Should You Offer?
Determining the right deposit amount requires a careful analysis of local market conditions and your budget. No federal law sets a minimum for this payment. However, offering too little can cause a seller to reject your purchase agreement immediately.
The Standard Percentage Rule
In most typical real estate markets, buyers offer between one and three percent of the total purchase price. For a home priced at half a million dollars, this translates to a deposit of $5,000 to $15,000. This standard range provides enough security for the seller without completely draining the buyer’s liquid savings.
Adjusting for Highly Competitive Markets
Hot seller’s markets often require much more aggressive financial tactics to win a bidding war. Buyers in highly desirable neighborhoods frequently increase their earnest money to five or even ten percent. A large deposit signals strong financial position and helps your offer stand out among competitors.
Considerations for New Construction
Buying a brand-new home directly from a production builder often involves completely different deposit rules. Builders typically require a flat fee or a higher percentage to cover custom upgrades. Carefully read the builder’s contract to understand their specific deposit requirements.
Where Does the Money Go During Escrow?
Never give an earnest money check directly to the seller under any circumstances. Handing cash directly to the homeowner opens the door to massive fraud and legal complications. Instead, a neutral third party must hold these funds until the transaction formally closes.
Typically, a title company, an escrow agent, or a real estate brokerage holds the money in a specialized trust account. This legally protected account ensures that neither the buyer nor the seller can access the funds prematurely. The escrow officer strictly follows the terms of the purchase contract when determining how to distribute the money eventually.
Once the transaction reaches the closing table, the earnest money doesn’t simply vanish. The escrow company applies the full deposit amount toward the buyer’s down payment or closing costs. Ultimately, the money you put down upfront directly reduces the amount of cash you must bring to closing.
How to Protect Your Earnest Money Deposit
Buyers risk losing their entire deposit if they carelessly break the rules outlined in the purchase contract. Real estate contracts contain specific contingency clauses designed to protect the buyer’s upfront investment. You must understand and closely monitor these contractual deadlines to keep your money perfectly safe.
The Home Inspection Contingency
This critical clause allows you to hire a professional inspector to evaluate the property’s physical condition. If the inspector uncovers massive structural flaws, you can legally cancel the contract and retrieve your deposit. However, you must formally withdraw your offer before the exact deadline specified in the inspection contingency.
The Financing and Appraisal Contingencies
Mortgage approvals are never fully guaranteed until underwriting is complete. A financing contingency ensures you get your money back if your lender ultimately denies your loan application. Similarly, an appraisal contingency protects you if the home values at less than your agreed-upon purchase price.
The Danger of Waiving Contingencies
In hyper-competitive markets, buyers often feel pressured to waive these protective clauses to win the home. Waiving contingencies means you agree to buy the home regardless of inspection results or loan denials. If you waive these rights and cannot close the deal, the seller will legally keep your entire deposit.
The Psychological Impact of a High Deposit
Real estate negotiations are heavily influenced by human psychology and perceived financial strength. A substantial earnest money deposit sends a powerful, unspoken message to the seller about your overall reliability. Sellers want peace of mind, and a large check provides immediate comfort during a highly stressful transition.
Standing Out in a Bidding War
When a seller receives five identical offers, the one with the highest upfront deposit usually wins. A larger deposit implies that the buyer has substantial cash reserves and is unlikely to face last-minute loan denials. Sellers will often accept a slightly lower purchase price if the earnest money is exceptionally high.
Building Trust with the Seller
Trust is a highly underrated component of any major financial transaction. Presenting a strong deposit shows the seller you respect their property and their time. This goodwill can help if you need to negotiate minor repairs after the home inspection.
Overcoming a Weak Mortgage Profile
Some buyers rely on government-backed loans that sellers often perceive as complicated or slow to close. A large upfront deposit can help offset the stigma of using an FHA or VA loan. A large cash commitment shows the seller you are financially stable, regardless of your loan type.
Common Mistakes Buyers Make with Deposits
One of the biggest mistakes buyers make is dragging their feet when submitting the initial funds. Most real estate contracts require you to submit the deposit within two or three business days of acceptance. Missing this deadline constitutes a breach of contract and allows the seller to cancel the deal immediately.
Another common error is using funds that a mortgage lender can’t easily verify. Never use a credit card cash advance or undocumented cash for your deposit. Lenders require a clear paper trail for all money involved in the transaction to comply with federal anti-money laundering laws.
Finally, buyers often misunderstand the strict timeline for removing contingencies. If you miss a deadline to request repairs, the contract often assumes you accept the property as-is. Always rely on your real estate agent to track these dates and send formal cancellation notices if necessary.
To keep your funds secure throughout the escrow process, act strategically. Follow these crucial best practices to protect your upfront investment from unnecessary risks:
- Always write the check to a verified title or escrow company, never directly to the seller.
- Track every contingency expiration date on a shared digital calendar.
- Never offer more liquid cash than you can comfortably afford to lose in a worst-case scenario.
- Consult a real estate attorney immediately if a dispute arises over the final deposit distribution.
What Happens if the Deal Falls Through?
Not every real estate transaction ends with a successful transfer of property ownership. When a deal collapses, releasing the earnest money becomes the top priority. The reason for the cancellation determines who ultimately gets to keep the contested funds.
When the Buyer Gets the Money Back
Buyers receive a full refund if they cancel the contract based on a protected, unexpired contingency. For example, if a title search reveals massive undisclosed liens, the buyer can walk away cleanly. The escrow company will require both parties to sign a cancellation agreement before releasing the funds back to the buyer.
When the Seller Keeps the Deposit
Sellers are entitled to the funds if the buyer gets cold feet and walks away without legal justification. This scenario is exactly why the earnest money system exists in the first place. The retained deposit compensates the seller for the time their home sat pending and unavailable to other buyers.
Resolving Deposit Disputes
Occasionally, both the buyer and the seller will stubbornly claim they are legally entitled to the deposit. Escrow companies will not act as judges; they will hold the money until the parties reach an agreement. If the parties cannot compromise, they must settle the dispute through formal mediation or binding arbitration.
Closing Points
The earnest money deposit is a fundamental pillar of any successful real estate transaction. It protects the seller’s time while showing the buyer has serious financial intent. By carefully calculating your offer amount, you can present a strong bid that stands out in a crowded market.
Protecting that investment requires a thorough understanding of your contractual rights and contingency deadlines. You must act diligently, monitor the escrow process, and never waive protections without fully grasping the financial risks. With the right strategy and professional guidance, your earnest money will become the foundation of your new home.